Ever wondered why your insurance bill in North Carolina is what it is? Well, you’re in the right place! Whether you’re a newcomer or a long-time resident, understanding the ins and outs of insurance rates in the Tar Heel State is crucial. We’ve compiled a comprehensive guide to help you navigate the complex world of insurance, ensuring you get the best bang for your buck.
Here at Backlinko, we know the value of a well-researched strategy. From auto to health insurance, and everything in between, we’ve dissected the factors that influence rates, compared top providers, and even peered into the future of the NC insurance market. So, buckle up as we take you on this insightful journey!
Overview of Insurance Types in NC
Did you know that 10% of Americans are uninsured? That’s a risky game, especially in a state like North Carolina where insurance is crucial. Let’s dive into the types of insurance available here.
From auto to home and health insurance, North Carolina offers a variety of options. But choosing the right one can feel overwhelming. Here is the deal: finding the best coverage means understanding the pros and cons of each type.
Auto Insurance Options
Auto insurance is mandatory in NC, and it covers more than just fender benders. There are different coverage options like liability, collision, and comprehensive. Liability insurance covers damages you cause to others. However, collision and comprehensive cover damages to your own car from accidents and other incidents like theft.
- Liability: Required by law, covers others’ damages.
- Collision: Covers your car in accidents, not mandatory.
- Comprehensive: Covers non-collision damages, optional but recommended.
Home Insurance Coverage
Your home is your castle, but disasters can strike. Home insurance in NC typically covers structure, personal property, and liability. The structure coverage protects the physical home. Personal property takes care of your belongings, while liability is there if someone gets injured on your property.
- Structure: Protects the building itself.
- Personal Property: Covers personal items inside the home.
- Liability: Protects against legal claims from injuries.
Health Insurance Plans
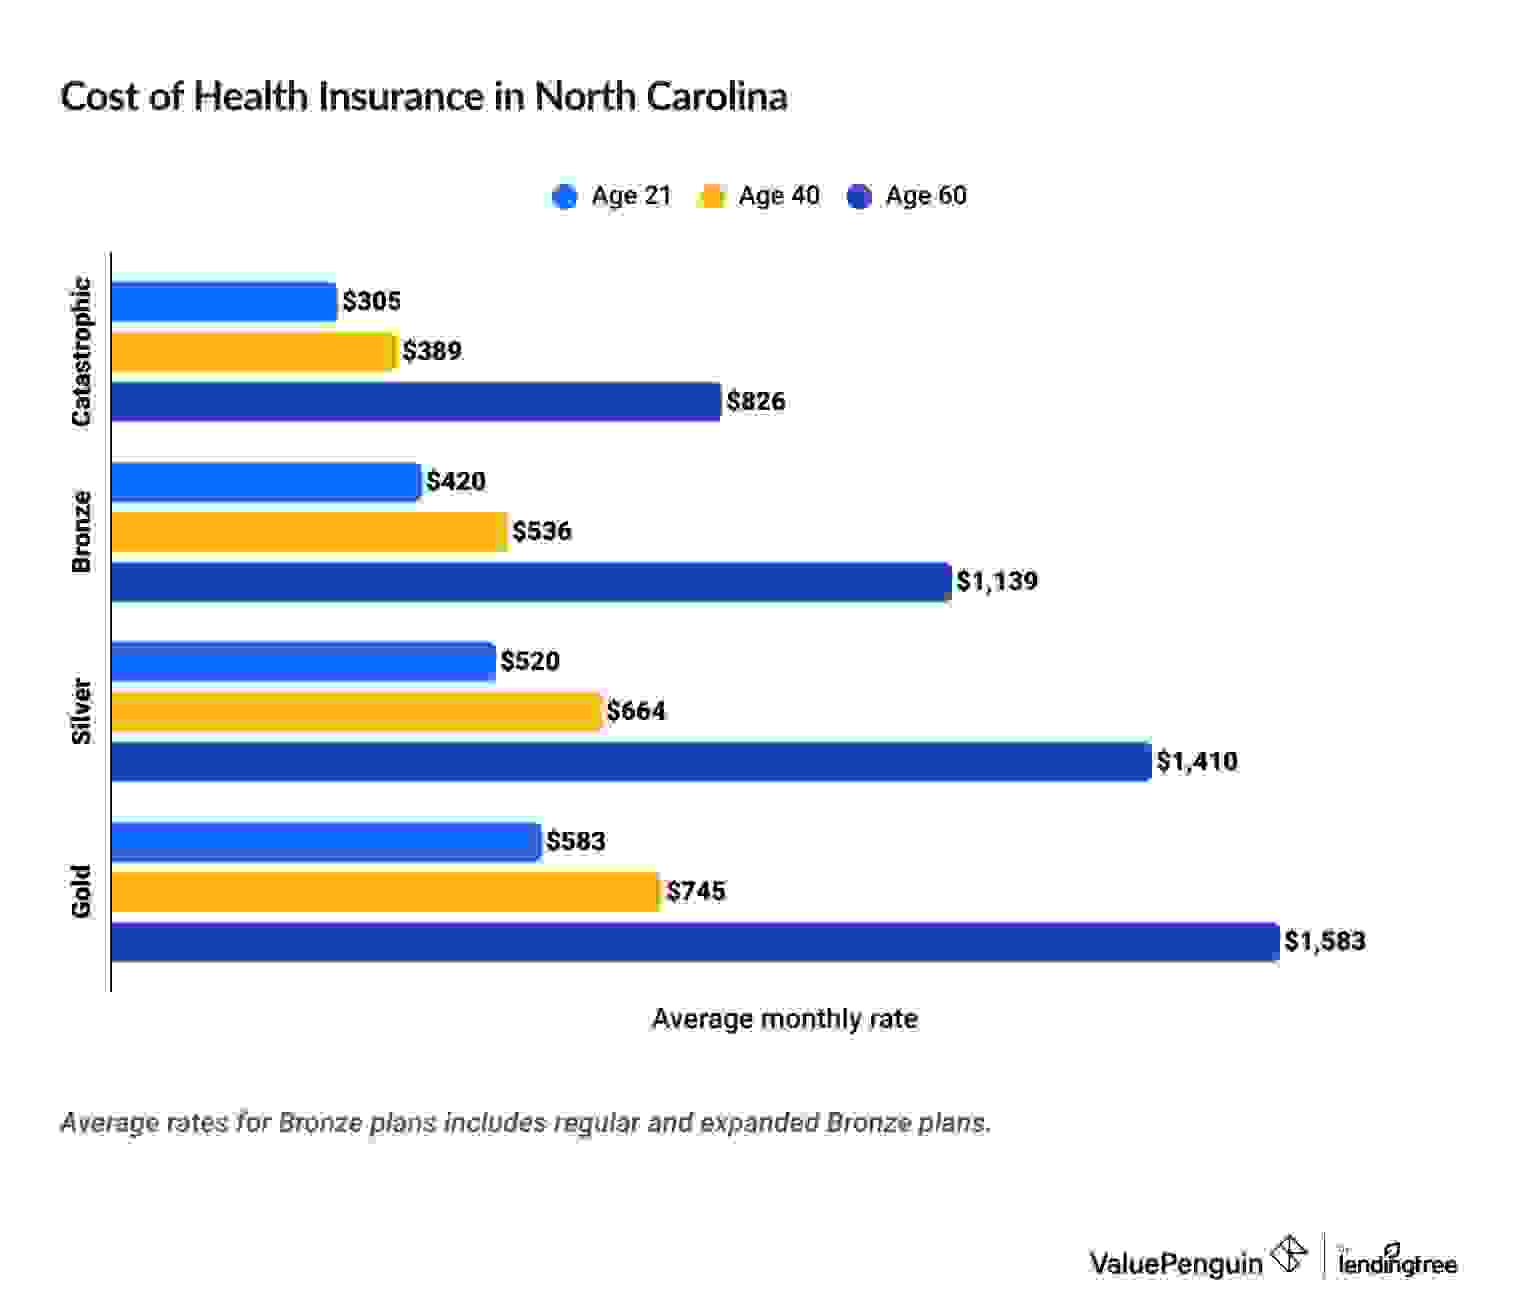
Health insurance is vital, and in NC, you have options. Plans range from HMOs, PPOs, to EPOs. HMOs are cost-effective but limit provider choices. PPOs offer flexibility at higher costs. EPOs strike a balance but usually require in-network services.
- HMO: Lower cost, fewer provider options.
- PPO: Flexible, higher premiums.
- EPO: Moderate cost, restricted network.
Pros and Cons of Each Insurance Type
Here’s a quick comparison to help you decide:
| Insurance Type | Pros | Cons |
|---|---|---|
| Auto | Protects against legal issues, covers repair costs | Can be expensive, mandatory minimums might be insufficient |
| Home | Comprehensive protection for property and belongings | Premiums can be high depending on coverage |
| Health | Access to healthcare, financial protection against medical expenses | Plans can be complicated, out-of-pocket costs vary |
Pro Tip: Always compare policies from multiple providers to get the best deal!
Factors Influencing Insurance Rates in NC
Did you know that your insurance rate in North Carolina could vary by hundreds of dollars? It’s true! Different factors play a significant role in determining what you pay.
Here is the deal: understanding these factors can save you a ton of money. Whether it’s your location, age, or driving history, each factor has its own weight in shaping your premium. Let’s break it down.
Location and Its Impact
Your zip code could make or break your budget. Urban areas in NC like Charlotte and Raleigh tend to have higher rates due to traffic density and crime rates. BUT, living in a rural area might lower your premium significantly because there’s less risk involved.
Age: The Number that Matters
It’s no secret that age plays a role in your insurance premium in NC. Younger drivers typically face higher rates. Why? They are considered high-risk due to lack of experience. However, as you age and gain experience, your rate could drop.
Pro Tip: If you’re under 25, consider joining a parent’s policy to save money.
How Driving History Shapes Your Rate
Have you had a speeding ticket or an accident? Your driving history is like a report card for insurers. A clean record can keep your rates low, while traffic violations can hike them up. BUT, maintaining a clean slate for a few years can help lower your premium.
Snapshot of Key Factors
Here’s a quick look at how different factors influence your insurance rates in NC:
| Factor | Example | Impact |
|---|---|---|
| Location | Urban (Charlotte) | Higher Rates |
| Age | 16-25 Years | Higher Rates |
| Driving History | 2 Tickets in a Year | Increased Rates |
Top Insurance Providers in North Carolina
Looking for the best insurance rates in North Carolina? You’ve landed in the right spot. Let’s dive into the top players in the state.
Whether you’re shopping for auto, home, or health insurance, knowing the right providers can save you a ton of cash. But here’s the deal: not all insurers are created equal. Some shine with stellar customer service, while others offer unbeatable rates. Let’s break it down.
Leading Insurance Companies in NC
When it comes to trusted names, State Farm, Allstate, and Nationwide are the heavyweights in North Carolina.
- State Farm: Known for excellent customer service and a wide range of coverage options.
- Allstate: Offers competitive rates and a user-friendly digital experience.
- Nationwide: Strong financial stability and comprehensive coverage plans.
Coverage Options and Customer Ratings
State Farm offers an extensive selection of policies from auto to renters insurance. Their customer service is consistently ranked as top-notch. Allstate doesn’t just compete on price; they also offer a seamless online platform for managing your policies.
Nationwide stands out with their “On Your Side” review, ensuring you’re getting the best deal and coverage. They also boast a strong financial stability rating, which is crucial for long-term protection.
Comparing Rates and Benefits
Here’s a closer look at how these providers stack up against each other.
| Provider | Average Rate | Customer Rating | Financial Stability |
|---|---|---|---|
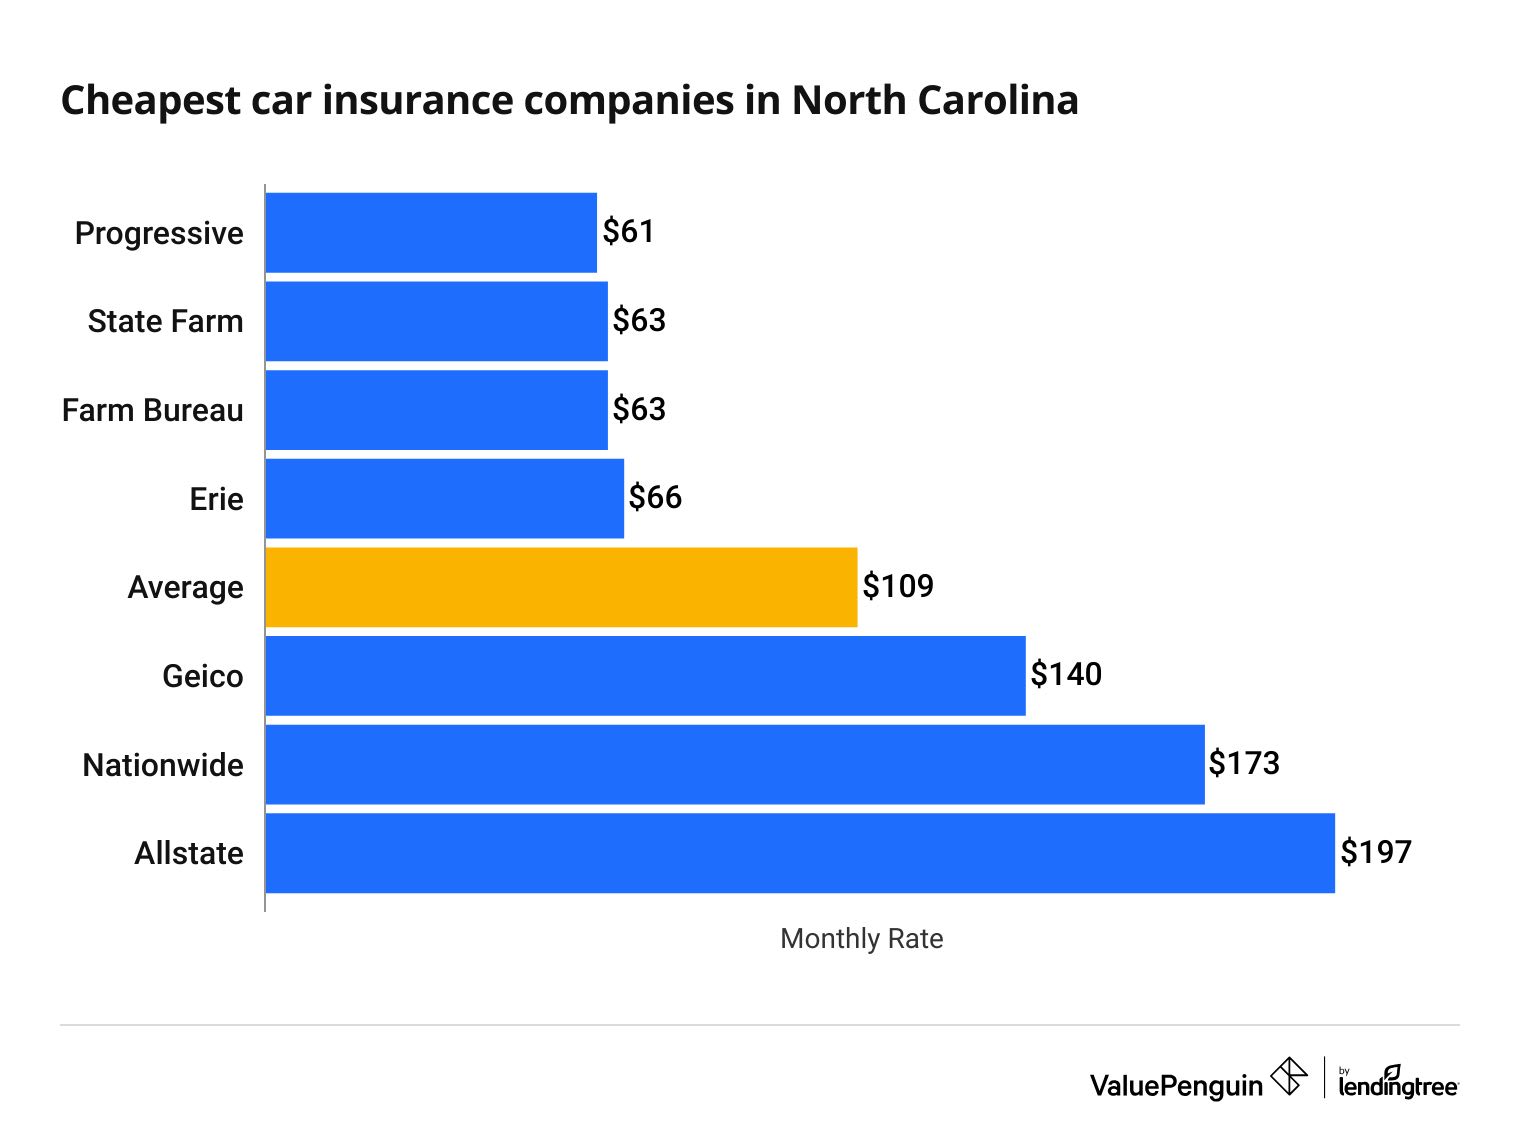
| State Farm | $1,200/year | 4.5/5 | A++ |
| Allstate | $1,150/year | 4.3/5 | A+ |
| Nationwide | $1,180/year | 4.4/5 | A+ |
Pro Tip: Always check for discounts and bundles to maximize savings with these top providers.
Methods to Secure the Best Insurance Rates
Think you’re paying too much for insurance in North Carolina? You’re probably right. Most people overpay without even realizing it. Let’s change that.
Securing the best insurance rates isn’t about luck. It’s about strategy. Here’s how you can slash those premiums without cutting coverage.
Effective Strategies to Reduce Insurance Premiums
Ever wonder why your premiums seem high? It’s because insurance companies bank on you not negotiating. Yet, with a few simple strategies, you can cut those costs significantly. Step #1: Shop around. Don’t settle for the first quote you get. Step #2: Increase your deductibles. A higher deductible means lower monthly premiums. But, make sure you have that amount set aside, just in case.
Step #3: Keep a clean record. A clean driving or claims record can mean big savings. Insurance companies love low-risk clients, and they reward them with lower rates.
Guidelines on Bundling Policies and Taking Advantage of Discounts
Insurance companies offer discounts if you bundle multiple policies with them. Home and auto is a classic combo. But there’s more to it. Check this out: some insurers will cut you a deal for bundling life insurance too. It’s an easy way to save.
- Ask about multi-car discounts if you have more than one vehicle.
- Consider group insurance plans through your employer or associations.
- Look for discounts for safety features in your home or vehicle.
Pro Tip: Always ask about available discounts. You’d be surprised how many exist that aren’t advertised.
Step-by-Step Procedure for Negotiating Better Rates
Negotiating isn’t just for car dealerships. You can negotiate your insurance rates too. Here’s how:
- Research the average rates for your coverage needs in your area. Knowledge is power.
- Contact your current insurer and ask if they can match or beat those rates. Be prepared to walk away.
- Use quotes from competitors as leverage. Insurance companies want to keep your business.
- Review and update your coverage needs regularly. Eliminating unnecessary coverage can lower your rates.
- Document everything. Written quotes and correspondence provide leverage.
Always stay informed and proactive. The best rates are just around the corner if you’re willing to reach for them.
Understanding Policy Terms and Conditions
Insurance policies can be tricky to decipher, especially with legal jargon. Have you ever wondered what you’re actually agreeing to when you sign on the dotted line?
Understanding the terms and conditions of your policy is crucial. It can mean the difference between a hassle-free claim and a denied one. Let’s dive into the essential elements of policy terms and conditions in North Carolina.
Essential Terms and Conditions in NC Insurance Policies
Every insurance policy comes with a set of terms and conditions. These terms artikel what is covered, the duration of coverage, and your responsibilities as a policyholder. Knowing these terms helps you avoid unpleasant surprises.
Coverage Limits: This is the maximum amount your insurer will pay for a covered loss. Make sure you know these limits, so you’re not caught off guard when making a claim.
Deductibles: This is the amount you pay out-of-pocket before your insurance kicks in. A higher deductible often means lower premiums, but it also means more costs upfront when filing a claim.
Check the fine print! Some policies have deductibles that apply to each individual claim, not just annually.
Common Exclusions and Limitations
Insurance policies also come with exclusions and limitations. These define what isn’t covered or situations where coverage is restricted. Ignoring these can lead to serious financial repercussions.
Natural Disasters: Many policies in NC exclude certain natural disasters like floods or earthquakes. If you live in a high-risk area, consider additional coverage.
Wear and Tear: Standard policies typically exclude regular wear and tear. This means you cannot claim for something that breaks down through regular use.
Always ask, “What does this policy NOT cover?” before purchasing. This question can save you from unexpected losses.
Key Policy Clauses to Watch For
Some clauses in your insurance policy demand extra attention. They can greatly affect how and when you can make a claim. Being aware of these can prevent future headaches.
Notice of Loss: Most policies require you to notify them within a certain timeframe after a loss. Missing this deadline could mean a denied claim.
Subrogation Clause: This allows the insurer to pursue a third party that caused a loss to the insured. Understand how this might affect you if you’re involved in an accident where another party is at fault.
Pro Tip: Always keep a copy of your policy, and review it annually to ensure it still meets your needs.
Future Trends in the NC Insurance Market
Ever wondered how the future of insurance rates is shaping up in North Carolina? You’re in for a roller-coaster ride as emerging trends and technology redefine the landscape.
The NC insurance market is being transformed by technological advancements and regulatory changes. These shifts are expected to significantly impact how insurance rates are determined. Let’s dive into the details.
The Role of Technology in Shaping Insurance Rates
Insurance used to be all about paper and phone calls. Now, technology is flipping the script. From AI-driven risk assessments to blockchain-backed claims processing, tech is streamlining operations and cutting costs. BUT, here’s the deal: as insurers become more efficient, you might see those savings passed along to you in the form of lower premiums.
Regulatory Changes: What to Expect
The North Carolina insurance landscape is not immune to the winds of regulatory change. Tighter data protection laws and evolving consumer rights can potentially influence rate structures. Here’s what you need to keep in mind: while certain regulations might push rates up, others could create a more competitive market, ultimately benefiting you.
Potential Future Rate Changes and Influencing Factors
Curious about how future trends might affect your insurance costs? Here’s a table that breaks it down for you:
| Trend | Expected Rate Change | Influencing Factors |
|---|---|---|
| AI-Powered Risk Assessment | Decrease | Improved accuracy, reduced fraud |
| Climate Change | Increase | Higher frequency of natural disasters |
| Regulatory Reforms | Variable | Data protection, consumer rights |
| Telematics and Usage-Based Insurance | Decrease | Personalized pricing models |
Pro Tip: Stay informed about regulatory changes and tech adoption in the insurance sector. Being proactive can help you snag the best rates.
Last Word
And there you have it, a deep dive into getting the best insurance rates in NC! Knowledge is power, and with this guide, you’re armed with the insights needed to make informed decisions. Remember, the insurance landscape is ever-evolving, and staying updated is key to ensuring that you’re always getting the best deal possible. Safe travels on your insurance journey!
FAQ
What factors influence insurance rates in North Carolina?
Insurance rates in NC are influenced by factors like your location, age, driving history, and the type of insurance you’re purchasing.
How can I lower my insurance premiums in North Carolina?
Consider bundling policies, maintaining a good credit score, and taking advantage of available discounts to lower your premiums.
Who are the top insurance providers in North Carolina?
Some leading providers include State Farm, Nationwide, and Geico, known for competitive rates and reliable coverage options.
What are common exclusions in NC insurance policies?
Typical exclusions might include wear and tear, floods in home insurance, and preexisting conditions in health insurance policies.
Are there any trends impacting future insurance rates in NC?
Yes, technological advancements and regulatory changes are set to influence future insurance rates in North Carolina.
