Are you tired of paying over-the-top premiums for your auto insurance in Massachusetts? Well, buckle up, because we’re about to take you on a ride through the ins and outs of auto insurance costs in the Bay State. Whether you’re a seasoned driver or new to the roads, understanding how much auto insurance sets you back and why can put the brakes on unnecessary spending.
In this comprehensive guide, we’re diving deep into the factors that influence auto insurance costs in Massachusetts. From your driving record to your zip code, each element plays a pivotal role in the rates you pay. So, let’s shift gears and explore how you can steer towards more affordable insurance premiums.
Factors Influencing Auto Insurance Costs in Massachusetts
Did you know that even a minor traffic violation could hike your auto insurance premium by up to 22%? Insurers in Massachusetts don’t mess around when it comes to calculating rates.
Understanding the factors that affect your insurance costs can help you make informed decisions and potentially lower your premium. Let’s dive into what really drives these costs.
Impact of Driving Record on Insurance Premiums
Your driving record is like your insurance report card. A clean record? Lower rates. But if you’ve got speeding tickets or accidents? Expect to pay more. Insurers view these as red flags that increase your risk. In Massachusetts, insurers can look back at least five years of your driving history.
Pro Tip:
Stay accident-free for a few years, and you could qualify for a “good driver” discount.
Age as a Factor in Insurance Rates
Age isn’t just a number; it’s a crucial factor in determining insurance costs. Younger drivers, especially those under 25, face higher rates due to perceived inexperience. As you cross 25, you may notice a significant drop in premiums, providing you maintain a good driving record.
But here’s the deal: even seniors can see increased rates if insurers perceive them as higher risk due to age-related factors.
Vehicle Type’s Role in Insurance Costs
The car you drive? It speaks volumes about your insurance rate. Sports cars, luxury vehicles, or cars with high theft rates generally have higher premiums. Why? They’re more expensive to repair or replace.
Step #1: Consider opting for a vehicle with a high safety rating and lower theft rate to keep costs down.
Location Within Massachusetts Influences Insurance Pricing
Where you park your car at night matters more than you think. Living in an urban area like Boston could mean higher rates due to increased risks of accidents and theft compared to rural areas.
Insurers use your ZIP code to assess risks, making urban dwellers pay more. But in areas with fewer claims and lower crime rates, you’ll find reasonable premiums.
Step #2: If you’re moving within the state, compare how different locations impact your insurance rate before you settle in.
Average Cost of Auto Insurance in Massachusetts
Did you know that Massachusetts drivers pay an arm and a leg for auto insurance? In 2023, the average annual premium in the state clocks in at $1,265. That’s higher than the national average.
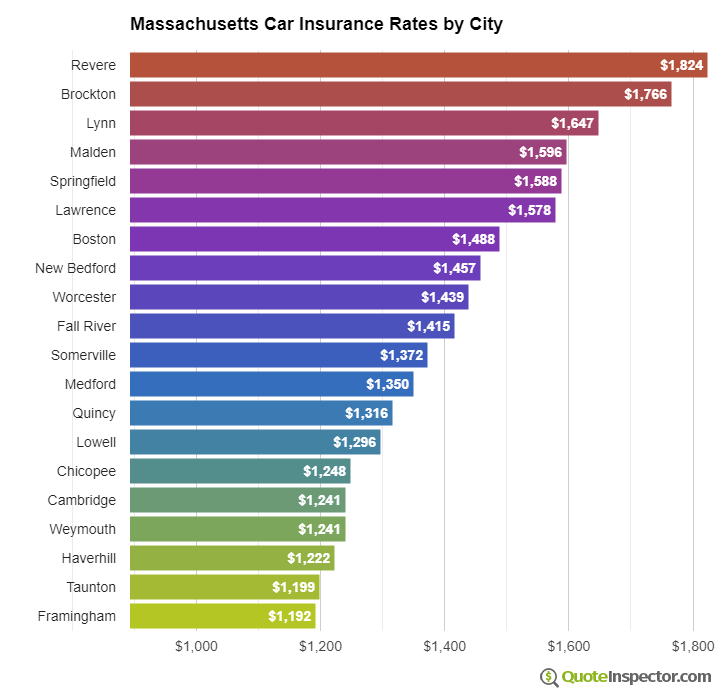
Here’s the deal: your location plays a major role in determining your insurance rate. If you’re residing in Boston, expect to pay more than someone in Springfield. But there’s more to it.
Cost Breakdown by Massachusetts Cities
Auto insurance rates can vary wildly depending on which Massachusetts city you call home. To give you a clearer picture, here’s a breakdown of the average costs across several key locations:
| City | Average Annual Cost |
|---|---|
| Boston | $1,550 |
| Worcester | $1,320 |
| Springfield | $1,180 |
| Lowell | $1,290 |
As you can see, Boston tops the chart with the highest average, while Springfield offers some relief with lower premiums.
Comparing Massachusetts to Neighboring States
Want to hear something interesting? Massachusetts residents are paying more than their neighbors. Compare: Rhode Island averages $1,450, while New Hampshire is at $1,150.
This makes Massachusetts more expensive than New Hampshire, but still cheaper than Rhode Island. So if you live near state borders, it might be worth investigating whether a move could save you some cash.
Historical Trends in Auto Insurance Pricing
Over the past decade, auto insurance costs in Massachusetts have seen a steady climb. In 2013, the average premium was around $1,050. Fast forward to today, and that figure has jumped by more than 20%.
BUT here’s the silver lining: the rate of increase has slowed in recent years. This could be due to increased competition or regulatory changes. So while prices are high, they aren’t skyrocketing like before.
Pro Tip: Keep a close eye on your policy renewal period. Rates can change significantly, so it’s smart to shop around before renewing.
Types of Auto Insurance Coverage Available in Massachusetts
Did you know that Massachusetts has some of the strictest auto insurance requirements in the US? You can’t just pick any policy and hit the road. You need to know the basics to make sure you’re not leaving gaps in your coverage.
Here’s the deal: understanding the different types of auto insurance coverage is crucial. In Massachusetts, you have a few key options: liability, collision, and comprehensive coverage. Each one serves a different purpose and comes with its own set of benefits and limitations.
Liability, Collision, and Comprehensive Coverage
Let’s break it down. Liability insurance is the foundation of your policy. It covers damages and injuries you cause to others in an accident. But what if your car needs repairs after a fender bender? That’s where collision coverage steps in, covering repairs to your car after an accident.
And then there’s comprehensive coverage. It’s like an all-risk policy for non-collision incidents, like theft or natural disasters. If a tree decides to crash onto your car during a storm, comprehensive coverage has your back.
Optional Coverages Offered by Insurers
You might think you’re all set with the basics, but wait! There’s more. Insurers in Massachusetts offer a range of optional coverages that can be game-changers:
- Gap Insurance – Covers the difference if your car’s loan amount is more than its value.
- Rental Reimbursement – Pays for a rental car while yours is in the shop.
- Roadside Assistance – Helps with towing, battery jump-starts, or even flat tire changes.
- Custom Parts and Equipment Coverage – Covers enhancements like a new sound system or custom wheels.
Pro Tip: Optional coverages can be tailored to fit your lifestyle and driving habits. Choose wisely!
Uninsured Motorist Coverage in Massachusetts
Ever wondered what happens if you’re hit by someone without insurance? That’s where uninsured motorist coverage comes into play. In Massachusetts, this coverage ensures that you’re not stuck with the bill if an uninsured driver ruins your day.
This coverage can also protect you if the at-fault driver doesn’t have enough insurance to cover your damages, known as underinsured motorist coverage.
Personal Injury Protection (PIP) Requirements
PIP is not just a suggestion in Massachusetts; it’s a requirement. It covers medical expenses, lost wages, and even replacement services regardless of who caused the accident.
Massachusetts mandates a minimum PIP coverage of $8,000. This coverage can be a lifesaver in covering immediate medical costs after an accident.
Auto Insurance Discounts in Massachusetts
Are you paying more than you should for auto insurance? I bet you are. Most people overlook the numerous discounts available that can slash your premiums significantly.
The truth is, Massachusetts offers a wide array of auto insurance discounts that can save you a pretty penny. These discounts aren’t just for the lucky few. They are accessible and can be a game-changer for your budget.
Common Discounts Offered to Policyholders
Insurance companies in Massachusetts love rewarding their customers. That’s why they offer several common discounts. For instance, you can shave off some bucks if you have a good driving record, are a student with high grades, or if your car has anti-theft devices. The key is to ask your insurer about every single discount they offer. Leave no stone unturned.
Bundling Policies for Maximum Savings
If you own a home, rent an apartment, or have another vehicle, consider bundling your policies. This is where the big savings come into play. Insurers offer multi-policy discounts if you insure your home and car with them. It’s like killing two birds with one stone. You save money and manage all your insurance needs in one place.
Pro Tip: Always compare the bundled rate to individual policies. Sometimes, it’s cheaper to bundle, but not always!
Qualifying for a Good Driver Discount
Good drivers get rewarded. If you have a clean driving record, you can potentially enjoy significant discounts. But how do you qualify? Step #1: No accidents. Step #2: No traffic violations. It’s that simple! Some insurers might even consider your mileage. Less driving can often mean fewer premiums. Who knew staying out of trouble could be this rewarding?
Benefits of Defensive Driving Courses
Here’s the deal: taking a defensive driving course can not only make you a better driver but also help you qualify for a discount. Many insurance companies offer discounts to policyholders who complete these courses. It’s a win-win. You become a safer driver and pay less. Massachusetts drivers, this is your chance to both improve your skills and cut down costs.
Steps to Obtain Auto Insurance in Massachusetts
Feeling overwhelmed by the thought of getting auto insurance in Massachusetts? You’re not alone. It’s crucial to understand the steps to secure the right coverage while saving cash.
Let’s break it down together. From comparing quotes to switching providers, I’ve got you covered.
The Procedure for Comparing Insurance Quotes
First things first, gather multiple quotes. You can do this by visiting individual insurance websites or using comparison tools. Look for quotes from at least three different companies. Why? Because prices can vary dramatically!
Next, examine the details. Don’t just look at the price; check what’s included in the coverage. Make sure you’re comparing apples to apples. Pay attention to deductibles, liability limits, and any additional perks.
Pro Tip: Use a comparison tool to save time and get a clearer picture of the best deals available.
Organize Step-by-Step for Applying for a New Policy
Ready to apply? Follow these steps:
- Choose your favorite quote from the comparison step.
- Contact the insurer directly or apply online. Most companies offer easy online applications.
- Provide all necessary documents such as your driver’s license and vehicle information.
- Review the policy terms carefully. Make sure it meets your needs before signing.
- Submit payment to activate your policy.
Remember, it’s not just about finding the cheapest option; you want a policy that offers the protection you need.
How to Switch Insurance Providers Efficiently
Think you could get a better deal elsewhere? Here’s how to make the switch without a hitch.
Begin by checking your current policy for any cancellation fees. Then, align the end date of your old policy with the start date of the new one to avoid any lapse in coverage. Finally, notify your current provider that you’re canceling.
Tips for Negotiating Better Insurance Rates
Negotiation can be your best friend when it comes to lowering your insurance costs. Here’s the deal: don’t be afraid to ask for discounts. Many insurers offer reduced rates for safe drivers, multiple policies, or even good grades for students.
Another trick? Increase your deductible. A higher deductible can lower your premium, but make sure you can afford the out-of-pocket cost if needed. Finally, stay informed about new products or discounts that may apply to you.
Pro Tip: Bundle your auto insurance with home insurance to unlock significant savings.
Impact of Legislation on Auto Insurance in Massachusetts
Did you know that local laws have a huge impact on what you pay for auto insurance in Massachusetts? Crazy, right? But it’s true. State regulations play a big role in shaping insurance policies and premiums.
Massachusetts mandates certain insurance coverage types and sets the framework for how insurers can operate within the state. These rules are designed to protect you as a consumer but can also influence the cost and availability of insurance options.
Overview of State Regulations Affecting Insurance
Massachusetts law requires all drivers to have minimum liability coverage. This includes bodily injury, property damage, and personal injury protection. If you skimp on this, you could face heavy fines and even lose your license. The state also regulates insurance filings and approves rates, ensuring they are not discriminatory and are based on sound actuarial principles. However, some people find these regulations can inadvertently limit their choices.
Recent Legislative Changes and Their Implications
Recent changes in legislation can be a game-changer. In 2021, Massachusetts introduced reforms focused on ride-sharing and autonomous vehicles. These changes mean you might need additional coverage if you drive for Uber or own a self-driving car. Insurance companies have adjusted their policies accordingly, which could impact your premium rates.
Process of Filing Insurance Claims in Massachusetts
Filing a claim in Massachusetts is straightforward but requires diligence. First, report the accident to your insurance company. Massachusetts follows a no-fault system, so your insurer pays for damages regardless of who caused the accident. Keep all documentation handy, including police reports and photos of the accident. This doesn’t just speed up the process; it helps you avoid unnecessary disputes.
- Report the accident immediately.
- Document everything thoroughly.
- Follow up diligently with your insurer.
Consumer Rights Regarding Auto Insurance
As a consumer, you have rights. Massachusetts law ensures that you can appeal denied claims and file complaints against insurers. You also have the right to receive clear policy documentation, which helps you understand exactly what you’re paying for. If you ever feel your rights are being violated, you can turn to the Massachusetts Division of Insurance for assistance.
Pro Tip: Always review your policy details annually. Laws and personal circumstances change, which might affect your coverage needs.
Final Summary
As you navigate the winding roads of auto insurance in Massachusetts, remember that knowledge is power. By understanding the myriad factors that influence your insurance costs, and taking advantage of discounts and strategies, you’re well on your way to optimizing your policy. So, go ahead and drive confidently, knowing you’ve got the right coverage at the best price!
Common Queries
What factors affect auto insurance costs in Massachusetts?
Several factors impact insurance costs, including driving record, age, vehicle type, and your location within Massachusetts.
How does age influence auto insurance rates in Massachusetts?
Younger drivers typically face higher premiums due to their inexperience, while rates generally decrease as drivers gain more experience and reach middle age.
Is location a significant factor in determining auto insurance costs?
Yes, living in urban areas with higher traffic volumes and accident rates can lead to higher insurance premiums compared to rural areas.
What are the average auto insurance costs in Massachusetts?
The average cost varies by city but remains competitive compared to neighboring states. Recent stats and trends can provide a more detailed breakdown.
How can I qualify for discounts on my auto insurance in Massachusetts?
Common discounts include those for good drivers, bundling policies, and completing defensive driving courses.
